Skip to content
Call +353 1 870 9210

Reinstatement cost assessments for Irish property

Our expertise lies in conducting commercial reinstatement cost assessments to help identify and reduce the risk of underinsurance in Ireland. We survey all types of commercial properties as well as high-value residential properties.

Request a reinstatement cost assessment Call +353 1 870 9210

RICS-regulated Chartered Building Surveyors. Inspections carried out nationwide.

What underinsurance can cost

Say it would cost €1,850,000 to rebuild a building, but it is insured for €1,200,000, a little under two thirds of that.

If the owner then makes a €100,000 claim, the average clause means the insurer may pay only part of it:

Claim made
€100,000
Insurer may pay
€64,865
Under insurance deduction
€35,135

Enquire now

A worked example. Whether and how average applies depends on the policy wording.

  • RICS, Royal Institution of Chartered Surveyors
  • SCSI, Society of Chartered Surveyors Ireland
  • The Insurance Institute of Ireland
  • Brokers Ireland Affinity Partner

Did you know that over 90% of Irish commercial properties are not insured for an appropriate amount?

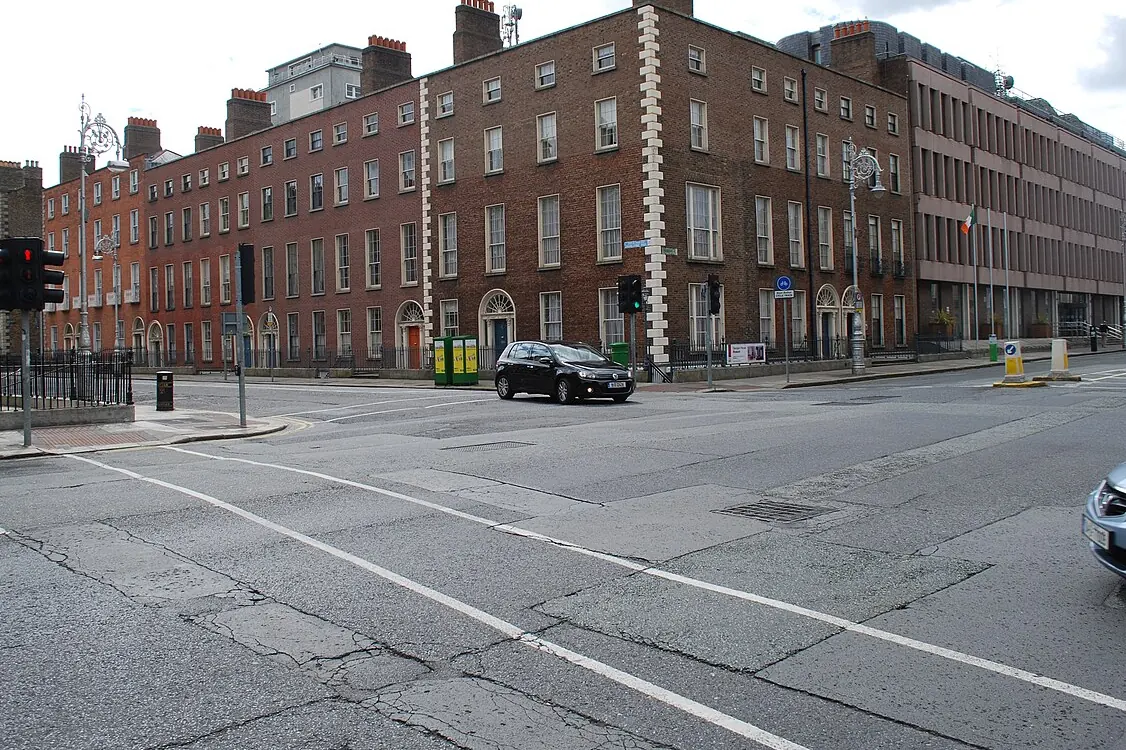
Terrace of red-brick Georgian buildings on a Dublin street corner

Why do I need a reinstatement cost assessment?

As a commercial property owner, you are responsible for providing the correct insurance value for your building to your broker. However, how are you meant to know the appropriate reinstatement cost? That’s what we do best.

Our team of RICS-regulated Chartered Building Surveyors provides professional assessments to help you maintain appropriate cover and reduce the risk of underinsurance.

How our reinstatement cost assessment service works

There’s a clause in your insurance policy you should understand

Insurance can be complicated. After all, it’s a contract and contracts are always full of conditions and clauses. When it comes to insuring your building there’s one clause you really need to know about.

It’s called the Average Clause and, put simply, it means if you insure your building for an amount that’s too low, your insurer can reduce how much they’ll pay out, in proportion to the shortfall.

How the average clause works on a partial loss
Building is insured for€500,000
It should be insured for€1,000,000
Underinsured by50%
You claim for€100,000
The insurer may pay€50,000

Whether and how average applies depends on your policy wording.

The risks of underinsurance explained

Signed document on a clipboard with a pen beside it on a desk
Surveyor in a hard hat carrying drawings towards a building on site

A professional approach to assessing your property’s reinstatement cost

We are here to explain the issue and address it in a professional and cost-effective way. As an RICS-regulated firm, a Chartered Surveyor will physically visit your site to assess and accurately report on reinstatement costs.

  1. Data collection

    A measured survey on site, with the construction, age, materials, services and any specialist elements of the building recorded.

  2. Analysis

    Materials, labour, demolition and site clearance, professional fees, statutory charges and the upgrades needed to meet current building standards.

  3. Reporting

    A clear written report showing the reinstatement cost, with the date and a description of the property, ready for your broker or insurer.

What happens at an on-site assessment

Who do we work with?

Commercial policyholders

Concerned that your property may be underinsured? Understand how the Average Clause may affect your insurance settlement. Take the first step to make sure your building is insured for the right amount by ordering a Reinstatement Cost Assessment.
Insurance brokers

Protect your clients and help them get their buildings’ sums insured right. We have a range of options for you. You can access discounted rates by opening an account with us, or quickly refer a client to us without handling payments.

Managing agents

We can help you confidently arrange the right level of cover for your client, whether it is for a single property or a large portfolio. We are committed to providing professional valuation solutions to meet your clients’ specific needs.

Insurance companies, underwriters and MGAs

Removal or waiver of the Average Clause, where offered, depends on the insurer and the policy wording. It can simplify a product and demonstrate customer care; however, we understand it’s equally important to ensure premiums are commensurate with risk. We’re ready to help you develop a programme to tackle inaccurate sums insured effectively.

Why is the reinstatement cost review important?

Construction costs can change materially over time, so reinstatement values should be reviewed regularly by a qualified professional.

How often should you get a reinstatement cost assessment?

Reinstatement cost assessment follow-up

After a thorough Reinstatement Cost Assessment, to ensure that your rebuild value remains correct and up to date, we recommend following the RICS best practice guidelines which state that a desk-based Reinstatement Cost Review should be completed 2 to 3 years after the full Reinstatement Cost Assessment.

Desktop reviews for buildings we have inspected

Guides on reinstatement costs and insurance

All articles

Request a reinstatement cost assessment

We welcome enquiries about commercial buildings, apartment developments and high-value homes from property owners, insurance brokers and managing agents. Send us a message and we’ll respond as soon as possible.

What happens next: we review your enquiry and send you a fee proposal and a proposed inspection date.

We use these details only to reply to your enquiry. See our Privacy Policy.